Yearly Archives: 2026

Remarks by Commissioner Uyeda on Modernizing Securities Regulation

Mark T. Uyeda is a Commissioner of the U.S. Securities and Exchange Commission. This post is based on his recent remarks. The views expressed in this post are those of Commissioner Uyeda and do not necessarily reflect those of the Securities and Exchange Commission or its staff.

Enhancing the Public Company Disclosure Framework

Thank you, Dave [Lynn], for that kind introduction.[1] I appreciate the opportunity to deliver the Alan B. Levenson Keynote Address, named in honor of the former director of the Division of Corporation Finance (Corp Fin). Alan started his service at the Commission during the tenure of Chairman Edward “Ned” Gadsby, who was appointed by President Eisenhower.[2] During his service, the Commission and its staff operated in a very different manner. It is hard to imagine a Corp Fin staff member today questioning a notorious figure such as former Teamsters president Jimmy Hoffa in a public hearing—but that is what Alan was able to do.

For lawyers involved in capital markets transactions, the annual Securities Regulation Institute organized by the Northwestern School of Law has become an important gathering. For those of us at the SEC, it represents an opportunity to engage with experienced securities law practitioners who can provide valuable feedback needed to develop sound regulatory policies. This is especially true as we revisit our rulebook to promote its effectiveness and reduce compliance burdens where regulatory obligations do not provide commensurate benefits for investors or our markets.

The obligation to weigh burdens versus benefits is not a personal preference or philosophy of mine. In fact, it is a legislative mandate. Congress tasked the SEC with this exact objective when it passed the National Securities Markets Improvement Act of 1996 (NSMIA).[3] NSMIA directs the Commission to consider whether an action will promote capital formation “whenever we are required to consider the impact of an action upon investor protection pursuant to a rulemaking function.”[4] It is unfortunate that the prior administration downplayed this directive, given the many misguided rulemakings that were proposed and adopted during that period.

READ MORE »

Law School Faculty Who Publish in Top Finance Journals

Michael Simkovic is Professor of Law and Accounting at the USC Gould School of Law. This is based on his recent report.

Legal academia is full of brilliant scholars doing important work. But a small group of law professors have done something rather unusual: getting past the notoriously demanding referees at the Journal of Finance, Journal of Financial Economics, and Review of Financial Studies—the most selective peer-reviewed finance journals in the world.
These three journals sit at the pinnacle of financial economics. They reject roughly 94% of submissions. The review process is grueling, often requiring multiple rounds of revision over several years. Success requires not just a good idea, but the technical chops to execute rigorous empirical or theoretical work that satisfies finance PhDs who’ve spent their careers in a mathematically demanding field—one that has produced Nobel laureates such as Eugene Fama, Robert Shiller, and Robert Merton.

For law professors—who typically face different training, different incentive structures, and different scholarly conversations—breaking through is a genuine accomplishment. It represents a bridge between two disciplines that don’t always speak the same language.

The first law professor to publish in a top-3 finance journal appears to be Harvard’s Mark Roe, who published seminal work on corporate ownership in the Journal of Financial Economics in 1990. The most published is Lucian Bebchuk (also at Harvard), with ten publications across these journals. But faculty at a growing number of institutions have shown they can compete at the same level—Berkeley, Columbia, Virginia, NYU, Northwestern, Yale, Stanford, Chicago, and others have all placed work in these journals. READ MORE »

Statement Commenting on the SEC’s Withdrawal from the No Action Process

Josh Zinner is the CEO, Timothy Smith is the Senior Policy Advisor, and Beth-ann Roth is the General Counsel at the Interfaith Center on Corporate Responsibility (ICCR). This post is based on a statement released by the ICCR and the Shareholder Rights Group.

The recent announcement by the SECʼs Division of Corporation Finance that its staff will not, during the 2026 proxy season, “… respond to no-action requests related to any basis for exclusion other than 14a-8(i)(1)” leaves both companies and investors in uncertain, uncharted waters. The lack of staff input deprives companies and proponents of an orderly and time-honored process.

We are concerned about the Division’s new approach and believe that companies would be unwise to rely on it as a basis to unilaterally decide to omit a resolution without considering further input from proponents.

For decades, shareholder proposals have been a key mechanism for investors to engage with the companies they own, and they have become an indispensable part of corporate governance. Shareholder engagement has encouraged many companies to adopt governance policies that are now widely adopted as best practices and recognized as important to long-term value creation. And resolutions relating to environmental and social impacts have led to important changes such as widespread adoption of human rights due diligence, corporate codes of conduct, and better management of climate risks.

READ MORE »

Controllers Unbound

Lucian Bebchuk is the James Barr Ames Professor of Law, Economics, and Finance and Director of the Program on Corporate Governance at Harvard Law School, and Kobi Kastiel is Professor of Law at Tel Aviv University. This post is based on their recent paper, and is part of the Controlling Shareholder Series; links to other posts in the series are available here. Related research from the Program on Corporate Governance includes Independent Directors and Controlling Shareholders by Lucian Bebchuk and Assaf Hamdani; How to Control Controller Conflicts by Lucian Bebchuk and Kobi Kastiel; The Untenable Case for Perpetual Dual-Class Stock by Lucian Bebchuk and Kobi Kastiel; and The Perils of Small-Minority Controllers by Lucian Bebchuk and Kobi Kastiel.

We just placed on SSRN our study Controllers Unbound. This post is part of a series of posts, based on this study, about the expected dire consequences of the recent relaxing of constraints on controlling shareholders.

Delaware’s recent SB21 legislation substantially weakened the constraints on controllers of public companies. Weak constraints exist in other states—notably Texas and Nevada—and Delaware’s legislation appears intended, at least in part, to induce companies to avoid reincorporating to those jurisdictions. These weaker constraints, our study concludes, should be expected to produce large and detrimental effects for public investors and the broader economy.

Even among those who have expressed concern about SB 21 and the loosening of controller constraints, we believe, there is substantial underestimation of the expected harm. This underestimation, we contend, is also prevalent among institutional investors. We believe it is crucial for all those interested in protecting public investors and ensuring the efficient operation of corporate America to fully understand the looming risks, and we seek to contribute to that understanding. We hope our work will help educate investors and market participants about the significant dark clouds gathering over the U.S. capital markets.

The analysis of our study has several components, which we outline in turn below.

READ MORE »

2025 Review of Shareholder Activism

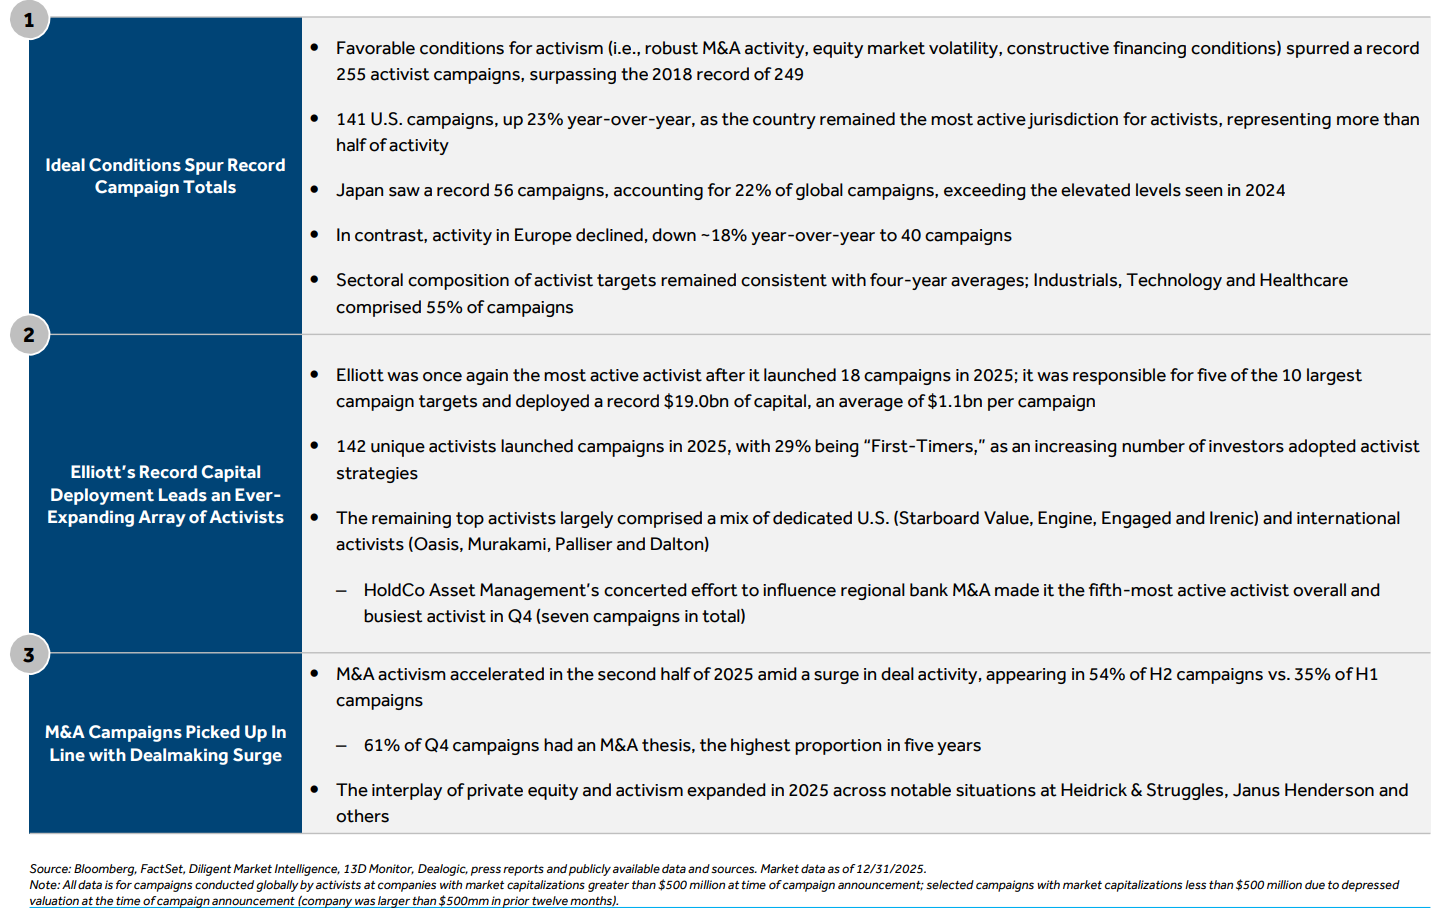
Jim Rossman is Global Head of Shareholder Advisory, Ryan Ferguson is a Director, and Abraham Axler is a Vice President at Barclays. This post is based on a Barclays memorandum by Mr. Rossman, Mr. Ferguson, Mr. Axler, Josh Jacobs, Dominic Pinion, and Olakunle Akande.

Observations on the Global Activism Environment in 2025

READ MORE »

The Debate on Performance Shares—Who Has It Right

Ani Huang is the CEO and Dr. Charles G. Tharp is a Senior Advisor at CHRO Association. This post is based on their CHRO memorandum.

After a decade of complete primacy, performance-based share units (PSUs) are undergoing a moment of intense scrutiny.

Investors like CII and Norges Bank are questioning whether:

  • PSUs should be the prevailing form of long-term incentives for CEOs, and
  • whether they are in fact tied to better performance

In response to investor input, proxy advisors like ISS and Glass Lewis are softening their requirements around performance-based equity. It can be tough to sort through all the differing perspectives. Here is a resource we hope will help clarify how the varying findings compare to each other, which questions are being asked (and answered) and key considerations for you in your work with the Compensation Committee.

  • ISS recently made headlines by breaking with its historic preference for performance-based pay, and investors seem increasingly willing to support long-vesting RSUs.
  • While studies suggest that companies with innovative LTI design perform better than peers, companies should view these results with caution and undertake their own analysis to determine if their approach to long-term incentives is optimal in view of their business strategy, competitive landscape, company culture, and talent objectives.
  • The Center believes that “best fit” should guide the design of executive compensation and encourages companies to resist being overly swayed by either prevailing practice or the headlines generated by limited research on LTI design and company performance.

READ MORE »

Pulse on Pay: 12 Years of CEO Pay

Margaret Hylas is a Managing Director, Leah Sine is a Consultant, and Michelle Wu is a Senior Associate Consultant at Semler Brossy. This post is based on their Semler Brossy memorandum.

OVERVIEW

Most executive pay levels analysis focuses on target equity grant values—essentially the accounting value at grant—rather than value realized when equity is earned. Assessing the trends and data underlying take-home equity value can offer boards a fresh perspective on their pay-for-performance alignment and pay program liquidity versus what is communicated to participants in target grant value.

Realized equity outcomes can be found in the Option Exercises and Stock Vested Tables in the CD&A, which reflect the value of an executive’s equity the moment it is off the table or earned. This report contains analysis on “In-Role S&P 500 CEOs” who have served for at least three years (so there is enough time for equity vesting to build up), and “Take-Home” equity compensation, including full-value shares at vest and options at exercise. Importantly, this analysis is differentiated from a “realizable” equity look, which would include the trending value of unvested equity awards.

READ MORE »

Rulemaking Petition Pursuant to the Holding Foreign Insiders Accountable Act (HFIAA)

Robert J. Jackson, Jr. is the Nathalie P. Urry Professor of Law at New York University School of Law, Bradford Levy is an Assistant Professor at the University of Chicago Booth School of Business, and Daniel J. Taylor is the Arthur Andersen Chaired Professor at the Wharton School of the University of Pennsylvania. This post is based on their recent petition to the U.S. Securities and Exchange Commission.

We are scholars of securities law and financial economics whose research led to the development and passage of the Holding Foreign Insiders Accountable Act (HFIAA or the Act).[1] Our joint work, Holding Foreign Insiders Accountable, first identified risks that investors face from insider trading at foreign firms listed in the United States.[2] Using a unique dataset, we estimated that foreign-firm insiders traded to avoid losses of over $10 billion. The evidence shows that opportunistic trading has been concentrated in companies domiciled in nonextradition countries beyond the reach of U.S. law—especially China.

We respectfully submit this rulemaking petition pursuant to Rule 192(a) of the Securities and Exchange Commission (SEC) Rules of Practice to ask that the Commission develop rules to give investors the insider-trading transparency at foreign firms that Congress and the President have mandated under the Act.

While trading of corporate insiders at a U.S.-domiciled public company is subject to rapid disclosure under Section 16(a) of the Securities Exchange Act of 1934, the SEC exempted foreign private issuers (FPIs) from that requirement.[3]As highlighted in our testimony before the Senate and the SEC’s Investor Advisory Committee, the SEC exempted FPIs from Section 16 long before China-domiciled companies became prominent among U.S.-listed foreign issuers.[4]

The Act eliminates that exemption, shining light on opportunistic trading in foreign companies that can harm American investors. In response, the SEC’s Staff issued a press release suggesting that the Act leaves in place an exemption for large FPI shareholders from disclosures otherwise required under Section 16.[5] The result of the Staff Press Release’s interpretation would be that large shareholders of U.S.-listed, Chinese-domiciled firms could avoid disclosing their trades to the public, while such disclosures would be required for shareholders of U.S. companies. Our petition instead urges the Commission to proceed as follows: READ MORE »

When Does an Officer’s Sexual Harassment of Employees Constitute a Fiduciary Breach?

Gail Weinstein is a Senior Counsel, Philip Richter is a Partner, and Steven Epstein is the Managing Partner at Fried, Frank, Harris, Shriver & Jacobson LLP. This post is based on a Fried Frank memorandum by Ms. Weinstein, Mr. Richter, Mr. Epstein, and Erica Jaffe, and is part of the Delaware law series; links to other posts in the series are available here.

Editor’s Note (January 29, 2026): At the authors’ request, the following paragraph has been added to reflect recent developments in Delaware law:

On January 16, 2026, the Court of Chancery issued its decision in Los Angeles City Employees’ Retirement System v. Sanford (“eXp”), which pointedly rebukes the Credit Glory decision. In eXp, Chancellor Kathaleen St.J. McCormick held, at the pleading stage of litigation, that the defendant directors and officers of eXp World, a real estate company, may have breached both their duty of loyalty, and their Caremark duties of oversight, by permitting, allegedly, rampant drugging and raping of the company’s real estate agents by its other agents. Based on eXp, the court’s jurisprudence is in flux as to whether sexual misconduct in the workplace should be viewed as personal misconduct governed by employment laws or, instead, may implicate directors’ and officers’ fiduciary duties.

In Brola v. Lundgren (Dec. 1, 2025), the Delaware Court of Chancery held that a director-officer’s sexual harassment of employees, which resulted in fines and other damages to the corporation, constituted personal misconduct and not a breach of his fiduciary duties to the corporation and its shareholders. Accordingly, the director-officer was not personally liable to the corporation for its losses. The decision thus limits the reach of the court’s 2023 seminal McDonald’s decision.

Key Points

  • A corporate officer’s sexual harassment of employees will not constitute a breach of fiduciary duties except under limited circumstances. Based on Brola, unless the officer’s corporate duties specifically included responsibility for ensuring against sexual harassment of employees, it is unlikely that his or her sexual harassment of employees would constitute a fiduciary breach.
  • The decision limits the McDonald’s decision. In McDonald’s, the court had held that an officer’s sexual harassment of employees violated his fiduciary duty of loyalty, as it was “selfish” conduct in which he engaged for his own personal gratification. In Brola, the court expressed the need for a “limiting principle” on this logic, lest every workplace misdeed based on personal interests— whether “a breakroom fistfight, a defamatory social media post, or theft of office supplies”—would constitute a fiduciary breach.
  • The decision will make it more difficult for plaintiffs to bring derivative actions against corporate officers who commit sexual harassment. Corporate officers who commit sexual harassment may be liable for sexual harassment under employment-related statutes, laws of the jurisdiction where the injury occurred, and/or contractual obligations to the company, but, except where their corporate duties specifically include preventing sexual harassment of employees, they should not be liable to the corporation for a breach of fiduciary duties.

READ MORE »

26 Trends Affecting Capital Markets in 2026

Anna Pinedo is a Partner at Mayer Brown LLP. This post is based on her Mayer Brown memorandum.

On this blog, we have commented quite a number of times regarding a number of trends affecting our capital markets—many of which have been a factor since the early 2000s and which have become more pronounced since the adoption of the Sarbanes-Oxley Act and related reforms.  For example, we have noted the decline in the number of U.S. public companies, and the rising significance of the private markets.  A report earlier this fall in the New York Times DealBook (Oct. 25, 2025) notes that private assets have more than doubled over 12 years, to $22 trillion in 2024 from $9.7 trillion in 2012.  The article notes that companies are staying private longer, waiting an average of 16 years to go public, 33 percent longer than a decade ago.  Since the change in administration, enhanced retail access to the private markets, or to the perceived attractive returns associated with private market assets, has been a focus of policymaker attention.  Of course, this is but one of several important conversations that likely will continue to influence markets in this coming year—below, we expand on this, and share some additional perspectives (all from just one lawyer’s, not banker’s, vantage point) on other trends.

READ MORE »

Page 58 of 63
1 … 48 49 50 51 52 53 54 55 56 57 58 59 60 61 62 63