Monthly Archives: September 2026

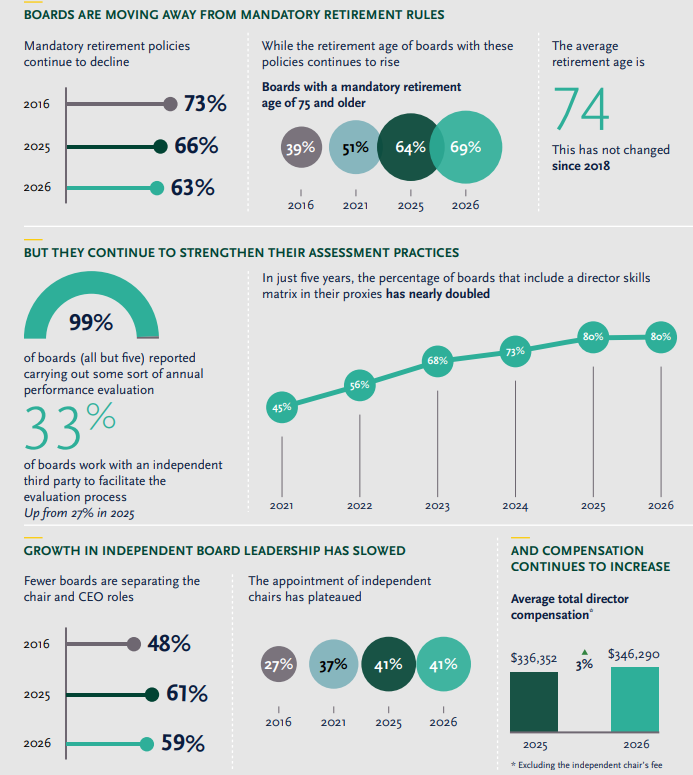
2026 U.S. Board Index Highlights

George Anderson and Rebecca Thornton are both Partners and Co-Leaders of the Board practice at Spencer Stuart. This post is based on a Spencer Stuart memorandum by Mr. Anderson, Ms. Thornton, and Ann Yerger, all at Spencer Stuart.

Board turnover and refreshment: What’s changed?

Refreshment continues to evolve gradually. While fewer boards rely on mandatory retirement policies, they are strengthening how they assess board effectiveness.

READ MORE »

Court of Chancery Enforces Earnout Procedural Protections

David A. Katz, Kevin S. Schwartz, and Jenna E. Levine are Partners at Wachtell Lipton Rosen & Katz. This post is based on a Wachtell Lipton memorandum by Mr. Katz, Mr. Schwartz, Ms. Levine, and Zachary David, all at Wachtell Lipton.

The Delaware Court of Chancery recently ordered a buyer to provide information necessary for sellers to participate in a negotiated earnout process, while rejecting the buyer’s effort to impose unwritten limits on earnout credit. Winton v. The North Highland Co. LLC, C.A. No. 2026-0138-LWW (Del. Ch. Sept. 18, 2026). The decision illustrates how the implied covenant of good faith and fair dealing, though narrowly and carefully applied under Delaware law, can preserve a negotiated earnout procedure without expanding the parties’ substantive written bargain.

North Highland, the buyer, acquired technology consulting firm The Bridge for cash, rolled equity, and an earnout tied in part to profits from new buyer projects. The agreement required the seller representative to notify buyer of potential qualifying projects and the parties to agree on their classification before client proposals were submitted. But it didn’t specify how the representative would obtain the information to do so. After closing, the buyer withheld pricing data and provided curated reports that excluded projects it unilaterally deemed ineligible.

The Court held that the implied covenant of good faith and fair dealing required the buyer to furnish the information necessary to make the agreed process work. The buyer could not insist on compliance with a notification condition while withholding the means to satisfy it. Taking care to confine the remedy, however, the Court held that the seller representative was entitled solely to periodic reports and disclosures before proposal deadlines to ensure its ability to identify and thus benefit from eligible projects, but not unrestricted real-time access to the buyer’s systems. Specific performance was warranted because damages could not reliably compensate for the lost opportunity to participate in the project classification process.

The Court also rejected the buyer’s efforts to exclude projects based on factors outside the agreement, such as where the work was performed, whom it was for, or whether the seller company participated. The requirement that the parties mutually agree on whether a project qualified did not give the buyer a substantive veto; it required them to apply the contractual revenue-based test. Although the buyer retained discretion over which projects to pursue and how to operate the business, it could not deny earnout credit on extra-contractual grounds.

As we have previously written, precise drafting of earnout procedures can help avoid costly litigation. Parties should specify what information must be supplied and when, how disagreements will be resolved, and ensure that those implementing the agreement understand its terms. The implied covenant remains a narrow safeguard, not a substitute for negotiated protections. But buyers should expect Delaware courts to enforce the procedures they agreed to, continuing their tradition of faithfully interpreting contracts as written and only implying terms strictly necessary to give effect to the parties’ explicit contractual bargain.
The 2026 Revision of Japan’s Corporate Governance Code: Toward Sustainable Growth and Medium to Long-Term Corporate Value Enhancement

Haruyuki Yamashita is the Head of Policy Engagement at the Tokyo Stock Exchange New York Office.

Corporate governance codes have been adopted in jurisdictions around the world as frameworks that systematically set out governance disciplines for companies. The United Kingdom, which is generally regarded as having one of the longest histories in this area, developed its framework against the backdrop of a series of financial and corporate scandals in the late 1980s and early 1990s. The 1992 Cadbury Report, which made recommendations concerning the effectiveness and reporting responsibilities of boards and the role of external auditors, marked an important starting point. In 1998, the Financial Reporting Council (FRC) issued the Combined Code as a statement of best practices in corporate governance. The OECD Principles of Corporate Governance followed in 1999 and have since served as practical guidance for policymakers in both OECD member and non-member jurisdictions.

READ MORE »

M&A, Activism and Corporate Governance

Matthew L. Ploszek and Adam M. Sanchez are Partners at Cravath, Swaine & Moore LLP. This post is based on a Cravath memorandum by Mr. Ploszek, Mr. Sanchez, Kimberley S. Drexler, Evan A. Hill, and Margaret T. Segall.

Mergers & Acquisitions

Why Divisive Mergers Are Gaining Popularity and How They Can Be Structured to Mitigate Risk

Although spin-offs and asset sales are the traditional means of separating business lines, divisive mergers provide an attractive option for companies looking to achieve contractual continuity and a clean separation of assets and liabilities. A divisive merger is a statutory mechanism that divides a company’s assets, liabilities and operations among two or more recipient entities, functioning in the reverse direction of a traditional merger. A key advantage is that divisive mergers allow complex businesses to avoid individually assigning each contract and obligation as required in traditional asset sales. However, this flexibility comes with unique risks of fraudulent transfer challenges and remedies.

Certain states, including Texas and Delaware, have statutory schemes that allow for divisive mergers. Texas first codified divisive mergers by broadening its definition of “merger” to include the division of one domestic entity into two or more organizations.[1] Under Texas law, all types of corporate entities (including corporations, partnerships and limited liability companies) may undergo a divisive merger, and the resulting entities may take any corporate form, even one different from that of the original entity.[2] Delaware, by contrast, allows only limited liability companies, limited partnerships and limited liability limited partnerships to effect divisive mergers, and the resulting entities must be of the same form as the original dividing entity.[3] Corporate entities may first undergo a change of corporate form in order to take advantage of the Delaware divisive merger statutes. In both states, divisive mergers are not considered assignments of assets or liabilities, potentially allowing companies to avoid triggering anti-assignment provisions,[4] reduce transaction costs and bypass third-party waivers or consents.

READ MORE »

Primer on Corporate Political Activity: The Risks Companies Face from Political Spending, and How to Manage Them

Bruce F. Freed is president of the Center for Political Accountability; and William S. Laufer is the Julian Aresty Endowed Professor and Director of the Carol at The Wharton School at the University of Pennsylvania. This post is based on their recent memorandum.

The primer was jointly produced by the Center for Political Accountability, an NGO leading the effort to bring transparency and accountability to corporate political spending, and The Impact, Value, and Sustainable Business Initiative at the Wharton School of the University of Pennsylvania (Wharton Impact).

The primer couldn’t be more timely as K Street and corporate America brace for possible post-midterm congressional investigations.  Business leaders and general counsels know that their companies’ political donations will be in the crosshairs.

For companies, the primer comes out as corruption has become a major political issue. A recent Gallup survey found a record-high 89 percent in the U.S. responded that government corruption, of which political spending is a part, is widespread. (Record-High 89% in U.S. Say Government Corruption Widespread)

READ MORE »

SEC Proposes to Modernize Proxy Solicitation Rules

Sebastian Alsheimer is a Partner and Head of the Shareholder Engagement and Activism Defense Practice, J.T. Ho is a Partner, and Julie Rong is an Associate at Cleary Gottlieb Steen & Hamilton LLP. This post is based on a Cleary Gottlieb memorandum by Mr. Alsheimer, Mr. Ho, Ms. Rong, Francesca Odell, Lillian Tsu, and Shuangjun Wang, all at Cleary Gottlieb.

On September 16, 2026, the SEC proposed a package of amendments intended to modernize the federal proxy solicitation rules. The proposal targets several paper-era or otherwise outdated requirements whose original rationale has largely been displaced by EDGAR, electronic communication and other changes in market practice, and would simplify annual meeting and proxy production and create flexibility in transaction and meeting calendars. As Commissioner Mark Uyeda stated, “Eliminating duplicative or outdated requirements reduces unnecessary compliance costs for issuers and intermediaries.”

READ MORE »

Staying the Course: The State of 2026 U.S. Sustainability Reports

Diana Lee is a Managing Director and Matt Filosa is a Senior Managing Director at Teneo. This post is based on a Teneo memorandum by Ms. Lee, Mr. Filosa, Rose James, Heidi Park, and Allie Ross, all at Teneo.

Introduction

It has been a year since we published our 2025 State of U.S. Sustainability Reports. The sustainability landscape remains marked by heightened scrutiny and uncertainty, as ongoing political conflicts and evolving global regulation continue to shape the expectations of key stakeholders.

For example, in the U.S., Republican state attorneys general continued to scrutinize company participation in climate initiatives, plastics and packaging and other sustainability-related activities. At the same time, California moved forward with mandatory climate disclosure requirements and Democratic states have scrutinized company rollbacks of diversity initiatives. Outside the U.S., the European Union continued efforts to simplify its sustainability reporting regime, while additional jurisdictions moved toward adopting disclosure requirements aligned with international frameworks (e.g., International Sustainability Standards Board (ISSB)). Amid this ongoing uncertainty and confusion globally, U.S. companies largely stayed the course on their sustainability reporting in 2026.

To help companies plan for reporting in 2027, we analyzed 250 sustainability reports from S&P 500 companies published in 2026. In this report, we provide (i) our study methodology; (ii) our top 10 takeaways from 2026 sustainability reports; and (iii) key statistics of 2026 sustainability reports.

READ MORE »

2026 Say on Pay Recap: Strong Results and Evolving Voting Dynamics

Emily Chase and Perla Cuevas are Consultants and Linda Pappas is a Principal at Pay Governance LLC. This post is based on their Pay Governance memorandum.

KEY TAKEAWAYS

  • 2026 is shaping up to be the strongest Say-on-Pay (SOP) season in recent history. Average S&P 500 SOP support reached 90.3%, the only time above 90% in the past 5 years.
  • Low support is less prevalent. Only 5% of companies received less than 70% support in 2026, down from 11% in 2022.
  • Strong S&P 500 total shareholder return (TSR) coincided with favorable SOP results. Since 2024, SOP failures have remained at 1% of S&P 500 proposals while one-, three-, and five-year TSR results were strongly positive.
  • Influence of proxy advisor SOP opposition continues to deteriorate. Institutional Shareholder Services (ISS) opposition declined to 9% year-over-year, while Glass Lewis (GL) opposition increased slightly to 13%. When both proxy advisors opposed SOP this season, only 19% failed to receive majority shareholder support, down from 50% in 2022.
  • The “big five” investors continue to take a selective approach to opposing S&P 500 SOP proposals and rely heavily on their proprietary voting frameworks. Top asset managers supported SOP at a rate of 95.6% in 2026 and deviated from proxy advisor SOP opposition in an overwhelming majority of cases.
  • As the proxy voting landscape continues to evolve, understanding investor expectations and effectively communicating rationale for compensation decisions is critical to strengthening SOP support.

READ MORE »

SEC Issues “Innovation Exemption” for Tokenized Securities

Colin D. Lloyd, Marie-Louise M. Huth and Mario Schollmeyer are Partners at Sullivan & Cromwell LLP. This post is based on a Sullivan & Cromwell memorandum by Mr. Lloyd, Ms. Huth, Mr. Schollmeyer, Natasha Vasan, James M. Shea Jr., and Rebecca J. Simmons, all at Sullivan & Cromwell.

Summary

On September 17, 2026, the Securities and Exchange Commission issued two five-year, conditional exemptions to facilitate the permissioned trading of “Tokenized NMS Stock” through automated market makers (“AMMs”) and liquidity pools (together, “AMM Liquidity Pools”):

  • an exemption from the definition of “exchange” for Tokenized Securities Venues (“TSVs”); and

  • an exemption from the definition of “dealer” for certain liquidity providers in an AMM Liquidity Pool that supplies liquidity to the liquidity pool in the form of Tokenized NMS Stock.

Together, these exemptions allow certain venues that use AMM Liquidity Pools to facilitate trading tokenized versions of certain listed U.S. stocks without registration as a national securities exchange or alternative trading system, while also permitting liquidity providers to deposit tokenized stock into those AMM Liquidity Pools without registering as dealers, in each case subject to several conditions and limitations as discussed below. The Innovation Exemption is effective immediately. The SEC is requesting comment on all aspects of the Innovation Exemption.

READ MORE »

Weekly Roundup: September 18-24, 2026


More from:

This roundup contains a collection of the posts published on the Forum during the week of September 18-24, 2026

Remarks by Chairman Atkins on 24-Hour Trading


Statement by Commissioner Peirce on the Innovation Exemption


Forced CEO Departures


The Risks of Designated Directorships—Current Guidance for Directors and Those Who Appoint Them


A Breakout Year for CVRs: 2025 and First-Half 2026 Trends in Life Sciences Public M&A


FDA and SEC Open a New Information-Sharing Channel: Implications for Public Life Sciences Companies


Compensation Clawbacks – Surveying the Disclosures to Date


SEC Proposes to Rescind Rule 14a-8


The CEO Decision: How PE Investors Select and Reassess Leaders from Entry to Exit


Dodiya v. Franklin and the Emerging Rules of the DGCL’s Section 144 Safe Harbors


Rescission of Rule 14a-8: Anticipating the Potential Evolution of Shareholder Engagement Strategies


Page 1 of 6
1 2 3 4 5 6